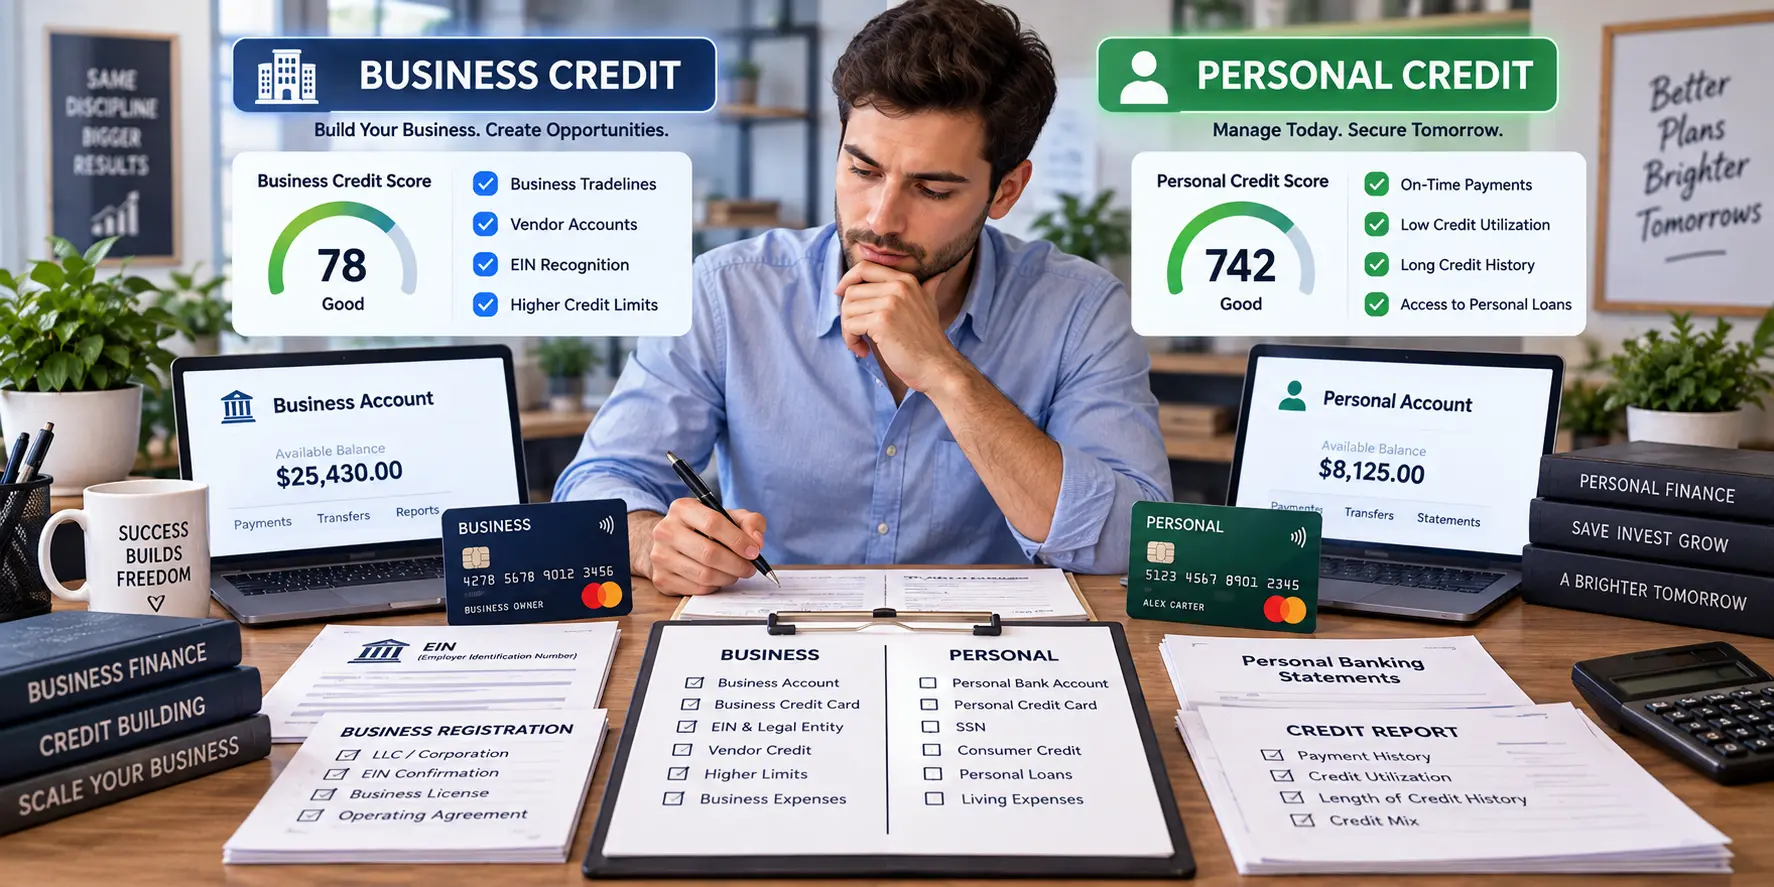
Understanding business credit vs personal credit helps owners separate two financial profiles that can influence different borrowing and commercial decisions. Personal credit generally reflects an individual’s borrowing history, while business credit relates to the credit activity and financial identity of a company. The two can sometimes interact, especially for newer businesses, but they are not the same thing.
Knowing the distinction can help business owners organize finances more clearly and understand what lenders, suppliers, and other parties may evaluate when extending credit.
What Is Personal Credit?
Personal credit is associated with an individual.
Consumer credit reports may contain information about personal credit accounts, payment history, balances, credit inquiries, and other reported activity. Credit scoring models can use information from these reports to produce consumer credit scores.
Banks, card issuers, lenders, landlords, and other organizations may review personal credit where permitted and relevant to a transaction.
A person’s credit history therefore follows the individual rather than a business they own.
What Is Business Credit?
Business credit relates to the credit profile and payment activity of a company.
Depending on the business and reporting arrangements, a commercial credit profile can contain information connected with supplier accounts, financing, payment experiences, company details, and other business credit activity.
The business may be identified through information such as its legal name, address, registration details, and relevant tax or business identification numbers.
However, simply registering a company does not automatically create a strong business credit history. Credit typically develops through financial activity that is actually reported to relevant commercial credit bureaus or agencies.
Business Credit vs Personal Credit: Main Differences
The clearest difference is whose financial behavior the credit profile represents.
Personal credit represents an individual borrower. Business credit is associated with a company.
This distinction affects several areas.
Identification
Personal credit is connected to an individual’s identifying information.
Business credit is associated with the company’s identity and may use business-specific information such as its legal name, address, and relevant identification numbers.
Credit Reporting
Consumer and commercial credit information may be maintained by different credit-reporting organizations and evaluated using different systems.
A strong personal credit history therefore does not automatically mean a business has an established commercial credit profile.
Financial Activity
Personal credit typically reflects consumer borrowing and repayment activity.
Business credit may reflect commercial financing, supplier arrangements, company payment experiences, and other qualifying business obligations.
Can Personal Credit Affect Business Financing?
Yes, it can in some circumstances.
A lender may consider an owner’s personal credit when evaluating financing for a new or small business, particularly when the company has limited operating history or an undeveloped business credit profile.
A personal guarantee may also make an individual responsible for repayment if the business does not meet the obligation.
The exact requirements vary by lender, financing product, company structure, and financial circumstances.
Therefore, owners should read financing terms carefully rather than assuming that borrowing under a business name automatically separates all personal responsibility.
Why Financial Separation Matters
Separating business and personal finances can make company transactions easier to identify and document.
A dedicated business bank account, appropriate bookkeeping records, and business-specific payment methods can help create a clearer financial trail.
This separation can make it easier to review company revenue and expenses, prepare financial records, and understand the business’s actual cash position.
Owners learning about financing, business banking, credit, cash flow, and other foundational management topics can discover more here through GrowBizLab’s broader collection of small-business information.
Financial separation by itself does not guarantee access to business credit, but it can support more organized financial management.
How Does a Business Begin Establishing Credit?
The process starts with establishing the business correctly and maintaining accurate, consistent information.
Depending on the company and jurisdiction, this can involve forming or registering the business appropriately, obtaining required identification numbers, opening suitable financial accounts, and keeping business records current.
The company can then build financial relationships relevant to its operations.
Some suppliers or creditors may report qualifying payment activity to commercial credit bureaus, while others may not. Business owners should not assume every account contributes to a commercial credit profile.
When considering a credit-building product or vendor account, it is useful to understand the terms, costs, reporting practices, and whether the account provides genuine operational value.
Payment History Still Matters
Whether dealing with personal or business credit, payment behavior is important.
Businesses should know when invoices, loans, credit accounts, and supplier obligations become due and manage them according to agreed terms.
A simple accounts-payable system can help prevent missed obligations caused by poor organization.
Owners should also review business credit reports where appropriate and available. Incorrect company information or unfamiliar reported accounts may require investigation through the relevant reporting organization’s procedures.
Business Credit Does Not Replace Cash Management
Credit can provide financial flexibility, but it should not be confused with cash flow or profitability.
A company may qualify for financing and still have weak operating cash flow. Likewise, access to a credit line does not necessarily mean the company can comfortably afford additional debt.
Borrowed funds create repayment obligations.
Before using business credit, owners should consider why financing is needed, how repayment will fit into expected cash flow, and whether the borrowed funds support a productive business purpose.
When Does the Difference Become More Important?
The distinction between personal and business credit often becomes increasingly relevant as a company develops.
A very small operation may initially rely heavily on the owner’s personal financial profile. Over time, the company may establish its own banking relationships, supplier accounts, financial records, and commercial credit history.
Growth can also create larger financing needs for equipment, inventory, hiring, technology, or expansion.
At that stage, having organized business finances and understanding how the company’s credit profile differs from the owner’s personal profile can become especially useful.
Business credit and personal credit serve related but distinct roles. Personal credit reflects the financial history of an individual, while business credit focuses on the company and its commercial financial activity. Understanding both helps owners evaluate financing terms, maintain clearer financial boundaries, and make borrowing decisions with a better understanding of which financial profile may be involved.